Facts checked Operator review
Casino document reviews
How do William Hill card withdrawals work? A document review
GB licence 39225 · checked 2026-09-19
Payment and operator marks are trademarks of their owners, shown for identification; no endorsement or partnership is implied.
How to read William Hill’s card-withdrawal documents: payment routing, pending and approved requests, Visa Direct conditions and bank tracing.
Review facts
- GB licence
- Account 39225 · current checked 19 September 2026
- What was read
- Public pages, logged out, UK locale
- Sources checked
- 15 September 2026
- Sources listed
- 9
- Method
- Editorial policy
Start with the status, then confirm the payment route
First establish whether the request is pending, approved or actually credited by the bank. Then confirm its destination and payment route. A published estimate alone cannot explain a particular account's delay.
William Hill's documents connect those stages to method selection, further checks and card tracing; this review turns them into an evidence map you can follow.
We first read the public material on 13 September 2026 and rechecked it for this media update on 15 September 2026. We did not open an account, deposit, gamble or request a withdrawal. Our focus is card withdrawals, with bank transfer mentioned where the routing policy requires it; this is not a comparison of every available payment method.
A performance comparison would need a properly defined dataset of actual outcomes. The findings concern what the documents explain, not a measured speed score.
Sources: William Hill: how withdrawals are processed; William Hill: Visa Direct; William Hill: tracing a card withdrawal with an ARN.
What the documents state
- Routing when one method is registered
- For an account with one registered method, William Hill says it returns funds there, using a bank transfer if that method cannot receive withdrawals.William Hill: how withdrawals are processed · as checked on
- Visa Direct threshold
- The page routes compatible withdrawals of £10,000 or less through Visa Direct; larger withdrawals use another route.William Hill: Visa Direct · as checked on
- The stated estimate
- For the eligible route, its stated usual arrival estimate is up to four hours from the request. It also explains that additional checks can extend a pending request, while an approved request still depends on the bank's processing.William Hill: Visa Direct · as checked on
- Card tracing thresholds
- For Visa Direct it refers to at least one full day, including weekends, but illustrates this with processing on 31 May and a request on 2 June. Other card withdrawals use a five-working-day threshold after issue.William Hill: tracing a card withdrawal with an ARN · as checked on
- The licensed entity
- The help-page footer identifies WHG (International) Limited for Great Britain and account 39225.Gambling Commission: WHG (International) Limited · as checked on
- Complaint handling
- It states a 24-hour acknowledgement for the second-opinion complaint and an endeavour to resolve within eight weeks. These are complaint-process statements, not expected withdrawal arrival times.William Hill: raising a complaint · as checked on
Each line restates what the linked public page said when it was read for this review. None of them is a measured outcome, and this review did not test withdrawal speed.
How to place your own case on this map
The order the sections below follow. It organises evidence; it cannot see an account or decide whether a particular delay is lawful.
Establish the status first
First establish whether the request is pending, approved or actually credited by the bank. A support message acknowledging a request is not proof that the bank has received it.
Confirm the destination and payment route
Then confirm its destination and payment route. This is a routing explanation, not a promise that any preferred destination will be available.
Record the three times separately
For a useful record, note the request time, any status change and the actual arrival separately. Nor is a bank statement enough to reveal how long the operator's earlier checks took.
Check whether a document request is outstanding
Record what was requested, when and why. Follow the current official instructions through the operator's verified channel; this publication and its worksheet do not receive account documents.
Ask which tracing route applies
Ask support to identify the applicable route and eligibility date if unclear. Keep the request reference and the bank's response together.
What the result means
An unknown status is a useful answer. It means the immediate task is to establish the last confirmed event, rather than assume either approval or rejection.
Which British service do these documents describe?
The help-page footer identifies WHG (International) Limited for Great Britain and account 39225. The Gambling Commission's record showed active remote casino activity, the active trading name “william hill online”, and the active domain www.williamhill.com when checked. These are specific observations from the register.
Its domain page did not separately list the help or games subdomain, and we have not completed a full regulatory-history audit.
Geography also changes the meaning of the help text. Several pages contain separate British and international instructions. We use the British branch where one is identified.
The regulatory discussion concerns Great Britain; a UK label elsewhere should not erase distinctions involving Northern Ireland. Before applying a payment instruction, match its customer category and product to the account in question.
Sources: William Hill: how withdrawals are processed; Gambling Commission: WHG (International) Limited; WHG domain names; WHG trading names.
The withdrawal destination is not always a free choice
For an account with one registered method, William Hill says it returns funds there, using a bank transfer if that method cannot receive withdrawals. With several methods, it describes trying the one with the greatest net deposit: deposits minus withdrawals. This is a routing explanation, not a promise that any preferred destination will be available.
Consider an invented ledger. Method A received £100 in deposits and £40 in previous withdrawals, leaving a £60 net deposit. Method B received £20 and no withdrawals, leaving £20.
A has the larger balance by that definition. The arithmetic helps explain the wording without claiming to reproduce William Hill's entire payments engine. An actual account can contain conditions the example does not represent.
Changing funding behaviour to manipulate routing is not part of this review.
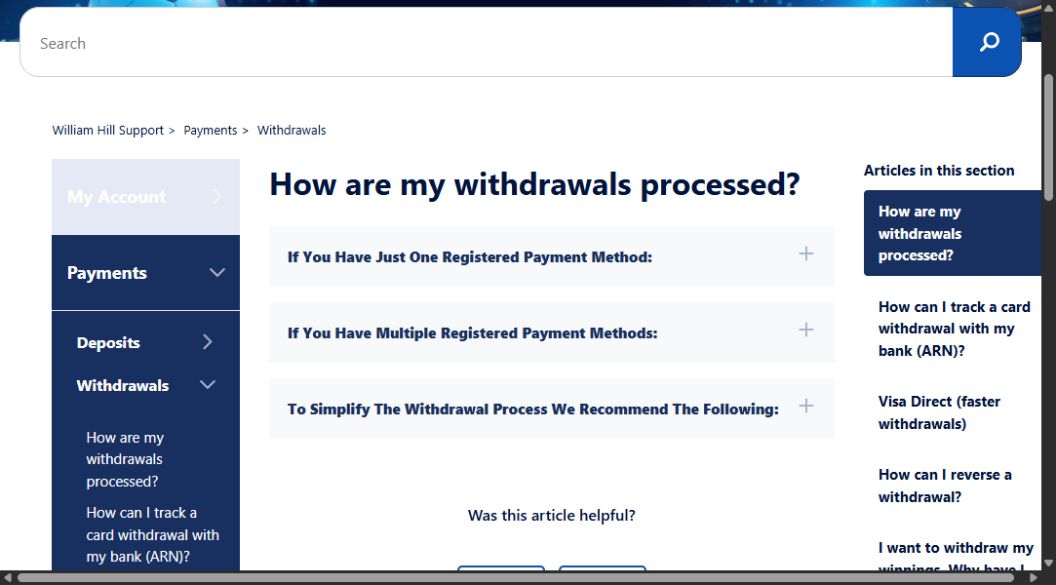
The support interface separates payment-method routing from card-tracking help. That is useful navigation, but the closed headings do not answer the routing question themselves: the reader must open the relevant section and check the separate tracking article. The screenshot documents this information structure, rather than a completed payment or a measured processing time.
The capture is dated 13 September 2026; we rechecked the linked public guidance on 15 September.
Sources: William Hill: how withdrawals are processed.
The invented ledger, as the section sets it out
| Method | Deposits | Previous withdrawals | Net deposit | Evidence |
|---|---|---|---|---|
| Method A | £100 | £40 | £60 | · William Hill: how withdrawals are processed |
| Method B | £20 | no withdrawals | £20 | · William Hill: how withdrawals are processed |
Changing funding behaviour to manipulate routing is not part of this review.
Pending and approved answer different questions
The Visa Direct document says that a compatible card and supporting bank are required and that funds return to the card used for the deposit. The page routes compatible withdrawals of £10,000 or less through Visa Direct; larger withdrawals use another route. For the eligible route, its stated usual arrival estimate is up to four hours from the request.
It also explains that additional checks can extend a pending request, while an approved request still depends on the bank's processing. Those qualifications belong beside the estimate.
For a useful record, note the request time, any status change and the actual arrival separately. A support message acknowledging a request is not proof that the bank has received it. Nor is a bank statement enough to reveal how long the operator's earlier checks took.
Payout Ledger's guide to the different withdrawal clocks explains why a single elapsed-time number often conceals the stage that needs attention.
Sources: William Hill: Visa Direct.
What to note beside each stage
The record the section above asks for. Keep it dated; a single elapsed-time number often conceals the stage that needs attention.
Ticks are kept only in this browser and are never sent anywhere.
Video transcript
The Payout Ledger — William Hill card withdrawals, documented 48-second silent, open-captioned original explainer. 00:00:00.000–00:00:07.000 William Hill card withdrawals. Public documents: no account or payment test. 00:00:07.000–00:00:15.000 A pending request can still require checks. Keep its reference and request time. 00:00:15.000–00:00:24.000 Approval is not confirmation of bank receipt. Keep the status change separate. 00:00:24.000–00:00:28.000 Ask which payment route was used and when the withdrawal was issued. 00:00:28.000–00:00:32.000 An ARN helps a bank trace a card transaction. It does not confirm bank receipt. 00:00:32.000–00:00:40.000 Confirm arrival from the bank record. Keep that event and its time separately. 00:00:40.000–00:00:48.000 Read the full review and source qualifications. This is a document explainer, not a speed test. Visual description: Original green and cream Payout Ledger typography accompanies three evidence markers labelled request, approval and bank credit. The current record is highlighted. An intervening issue-and-trace explanation identifies the payment route and ARN without depicting an actual payment interface. Marker spacing does not represent processing time. No operator screenshots, logos, gameplay, recorded account events, music or narration appear. Sources: William Hill Support, Visa Direct (faster withdrawals); How can I track a card withdrawal with my bank (ARN)? Public documents checked 15 September 2026. Full source links and qualifications are supplied in the accompanying article.
Read document requests alongside the verification rules
William Hill lists changed payment methods, inactivity and payment-ownership questions among reasons for requesting documents. Its page gives evidence requirements for different circumstances. Follow the current official instructions through the operator's verified channel; this publication and its worksheet do not receive account documents.
The Gambling Commission says online businesses must verify age and identity before gambling. Age and identity evidence that could have been requested earlier cannot simply become a new condition of withdrawal, although later legal obligations can require further information.
That distinction prevents two equally weak conclusions: that every document request is improper, or that any delay is justified merely by calling it verification. Record what was requested, when and why. Our identity-check guide gives a separate framework for organising that chronology without trying to decide an individual dispute.
Sources: William Hill: documents requested for a withdrawal; Gambling Commission: age, ID and financial verification.
The terms this review uses
- Pending
- A request the operator has received but not completed. Additional checks can extend a pending request.
- Approved
- The operator's approval of the request. An approved request still depends on the bank's processing, so it is not the same as money received.
- Net deposit
- Deposits minus withdrawals. With several methods, William Hill describes trying the one with the greatest net deposit.
- Visa Direct
- The route the page uses for compatible withdrawals of £10,000 or less. A compatible card and supporting bank are required, and funds return to the card used for the deposit.
- ARN
- An Acquirer's Reference Number, used by a bank to trace a card transaction.
A card trace is a separate step with its own evidence
An ARN is an Acquirer's Reference Number, used by a bank to trace a card transaction. William Hill's ARN page distinguishes Visa Direct from other card withdrawals. For Visa Direct it refers to at least one full day, including weekends, but illustrates this with processing on 31 May and a request on 2 June.
Other card withdrawals use a five-working-day threshold after issue.
The wording and example should be read together. We have not converted them into a deadline calculator, because an exact hour-by-hour interpretation would add precision the source does not supply. Ask support to identify the applicable route and eligibility date if unclear.
Keep the request reference and the bank's response together. A trace can investigate where a transaction sits; possession of a reference is not proof that money has already reached the account.
Sources: William Hill: tracing a card withdrawal with an ARN.
Escalation has a different purpose from payment tracing
The complaints page has a distinct UK section: begin with customer service, then seek a second opinion if the outcome is unsatisfactory, with IBAS identified as an external adjudication route. It states a 24-hour acknowledgement for the second-opinion complaint and an endeavour to resolve within eight weeks. These are complaint-process statements, not expected withdrawal arrival times.
The same page's non-UK branch uses different arrangements.
A useful complaint record separates the disputed action from the requested remedy. For example, identify the transaction and the unanswered question about its status, then attach the relevant correspondence through the official channel. Avoid treating a queue of repeated chats as a clear chronology.
A dated record makes it easier to see what response has already been given and which part of the issue remains unresolved.
Sources: William Hill: raising a complaint.
Use the stage worksheet as a record prompt
The offline worksheet below asks only which stage has actually been observed and whether a document request is outstanding. It suggests what evidence to organise next. It asks for no amounts, names, card details or identification, sends no requests and saves nothing between visits.
It cannot see a William Hill account or decide whether a particular delay is lawful.
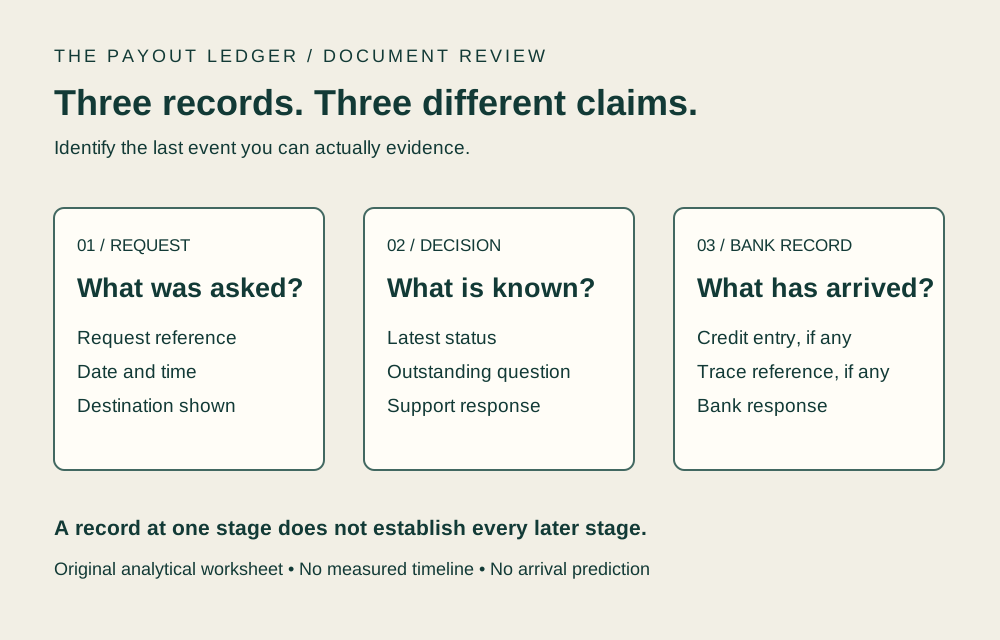
An unknown status is a useful answer. It means the immediate task is to establish the last confirmed event, rather than assume either approval or rejection. The diagram likewise shows evidence categories, not a measured average customer journey.
Keep source links and dated messages with any private record you maintain; do not upload sensitive records to a public review page or an unrelated calculator.
Choose the last confirmed withdrawal stage to see evidence prompts.
What would change this assessment?
The documents provide a usable map of method selection, status and card tracing. Their main limitation for a speed review is the absence of a sample with a denominator, payment-method breakdown and clearly defined start and finish points. We therefore cannot say what proportion of withdrawals meet an estimate, how performance varies, or whether a different casino would be quicker.
A future update should revisit the linked policies, recheck the specific domain and operator records and record material wording changes. Any genuine transaction research would need a separate disclosed method and should never be invented to fill a review template.
For now, the article's contribution is narrower and practical: identify the stage, preserve the evidence and apply the correct market-specific document before drawing a conclusion.
Questions answered
Has Payout Ledger tested William Hill withdrawal speeds?
No. This review examines public documents first checked on 13 September 2026 and rechecked on 15 September 2026. It reports no account test, measured arrival time or average payout speed.
Does approved mean the withdrawal has arrived?
An operator approval and a bank credit are different events. Compare the actual status record with the bank transaction rather than using either one as proof of both.
Why is my William Hill withdrawal still pending?
William Hill’s guidance says extra internal checks, including possible identification requests, can extend a pending request. The reason for your specific request needs confirmation through the official account or support channel.
What is an ARN?
An ARN is an Acquirer's Reference Number, used by a bank to trace a card transaction. A trace can investigate where a transaction sits; possession of a reference is not proof that money has already reached the account.
Which card withdrawals go through Visa Direct?
The Visa Direct document says that a compatible card and supporting bank are required and that funds return to the card used for the deposit. The page routes compatible withdrawals of £10,000 or less through Visa Direct; larger withdrawals use another route.
How does William Hill say a complaint is handled?
The complaints page has a distinct UK section: begin with customer service, then seek a second opinion if the outcome is unsatisfactory, with IBAS identified as an external adjudication route. It states a 24-hour acknowledgement for the second-opinion complaint and an endeavour to resolve within eight weeks. These are complaint-process statements, not expected withdrawal arrival times.
Payment sources
- William Hill: how withdrawals are processed
- William Hill: Visa Direct
- William Hill: tracing a card withdrawal with an ARN
- William Hill: documents requested for a withdrawal
- Gambling Commission: age, ID and financial verification
- William Hill: raising a complaint
- Gambling Commission: WHG (International) Limited
- Gambling Commission: WHG domain names
- Gambling Commission: WHG trading names
Continue reading
Withdrawal clocks: the operator's clock, the bank's clock, and what the terms say
A withdrawal has at least two clocks, and an identity check sits in front of both. Licence condition 17.1.1 and Pay.UK's own scheme page settle which clock may start when.
Read Withdrawal clocks: the operator's clock, the bank's clock, and what the terms say
Identity checks and withdrawals: the condition, the guidance and the scope
An identity check belongs at registration, not at the cashier. Licence condition 17.1.1 puts name, address and date of birth before any gambling, and says a withdrawal request must not trigger information that could reasonably have been asked for earlier.
Read Identity checks and withdrawals: the condition, the guidance and the scope
How long do casino withdrawals take? What ten UK operators publish, and which clock each window measures
Ten UK operators’ published withdrawal windows by payment method, quoted from their help pages on 18 September 2026, with the operator’s processing clock separated from the bank’s.
Read How long do casino withdrawals take? What ten UK operators publish, and which clock each window measures
Build a complaint record for a delayed casino withdrawal
The withdrawal request and the complaint start different clocks. Keep the payment evidence, the operator’s response and the escalation record together without assuming what caused the delay.
Read Build a complaint record for a delayed casino withdrawal
An identity check and a source-of-funds request answer different questions
A passport can establish identity without explaining a transfer. Sort a casino document request by the question it asks, then keep a receipt for the evidence supplied.
Read An identity check and a source-of-funds request answer different questions
Continue reading
How long do casino withdrawals take? What ten UK operators publish, and which clock each window measures
Ten UK operators’ published withdrawal windows by payment method, quoted from their help pages on 18 September 2026, with the operator’s processing clock separated from the bank’s.
Read How long do casino withdrawals take? What ten UK operators publish, and which clock each window measuresBuild a complaint record for a delayed casino withdrawal
The withdrawal request and the complaint start different clocks. Keep the payment evidence, the operator’s response and the escalation record together without assuming what caused the delay.
Read Build a complaint record for a delayed casino withdrawalAn identity check and a source-of-funds request answer different questions
A passport can establish identity without explaining a transfer. Sort a casino document request by the question it asks, then keep a receipt for the evidence supplied.
Read An identity check and a source-of-funds request answer different questionsWithdrawal clocks: the operator's clock, the bank's clock, and what the terms say
Identity checks and withdrawals: the condition, the guidance and the scope
Build a complaint record for a delayed casino withdrawal
An identity check and a source-of-funds request answer different questions